Three directions for David Bourne
Same bones underneath, three different personalities. The specialism toggle swaps the selling sections so you can see each one carrying either niche. Photographs are stand-ins to show the shape of the page — David's own will replace them.
Today's site, for comparison
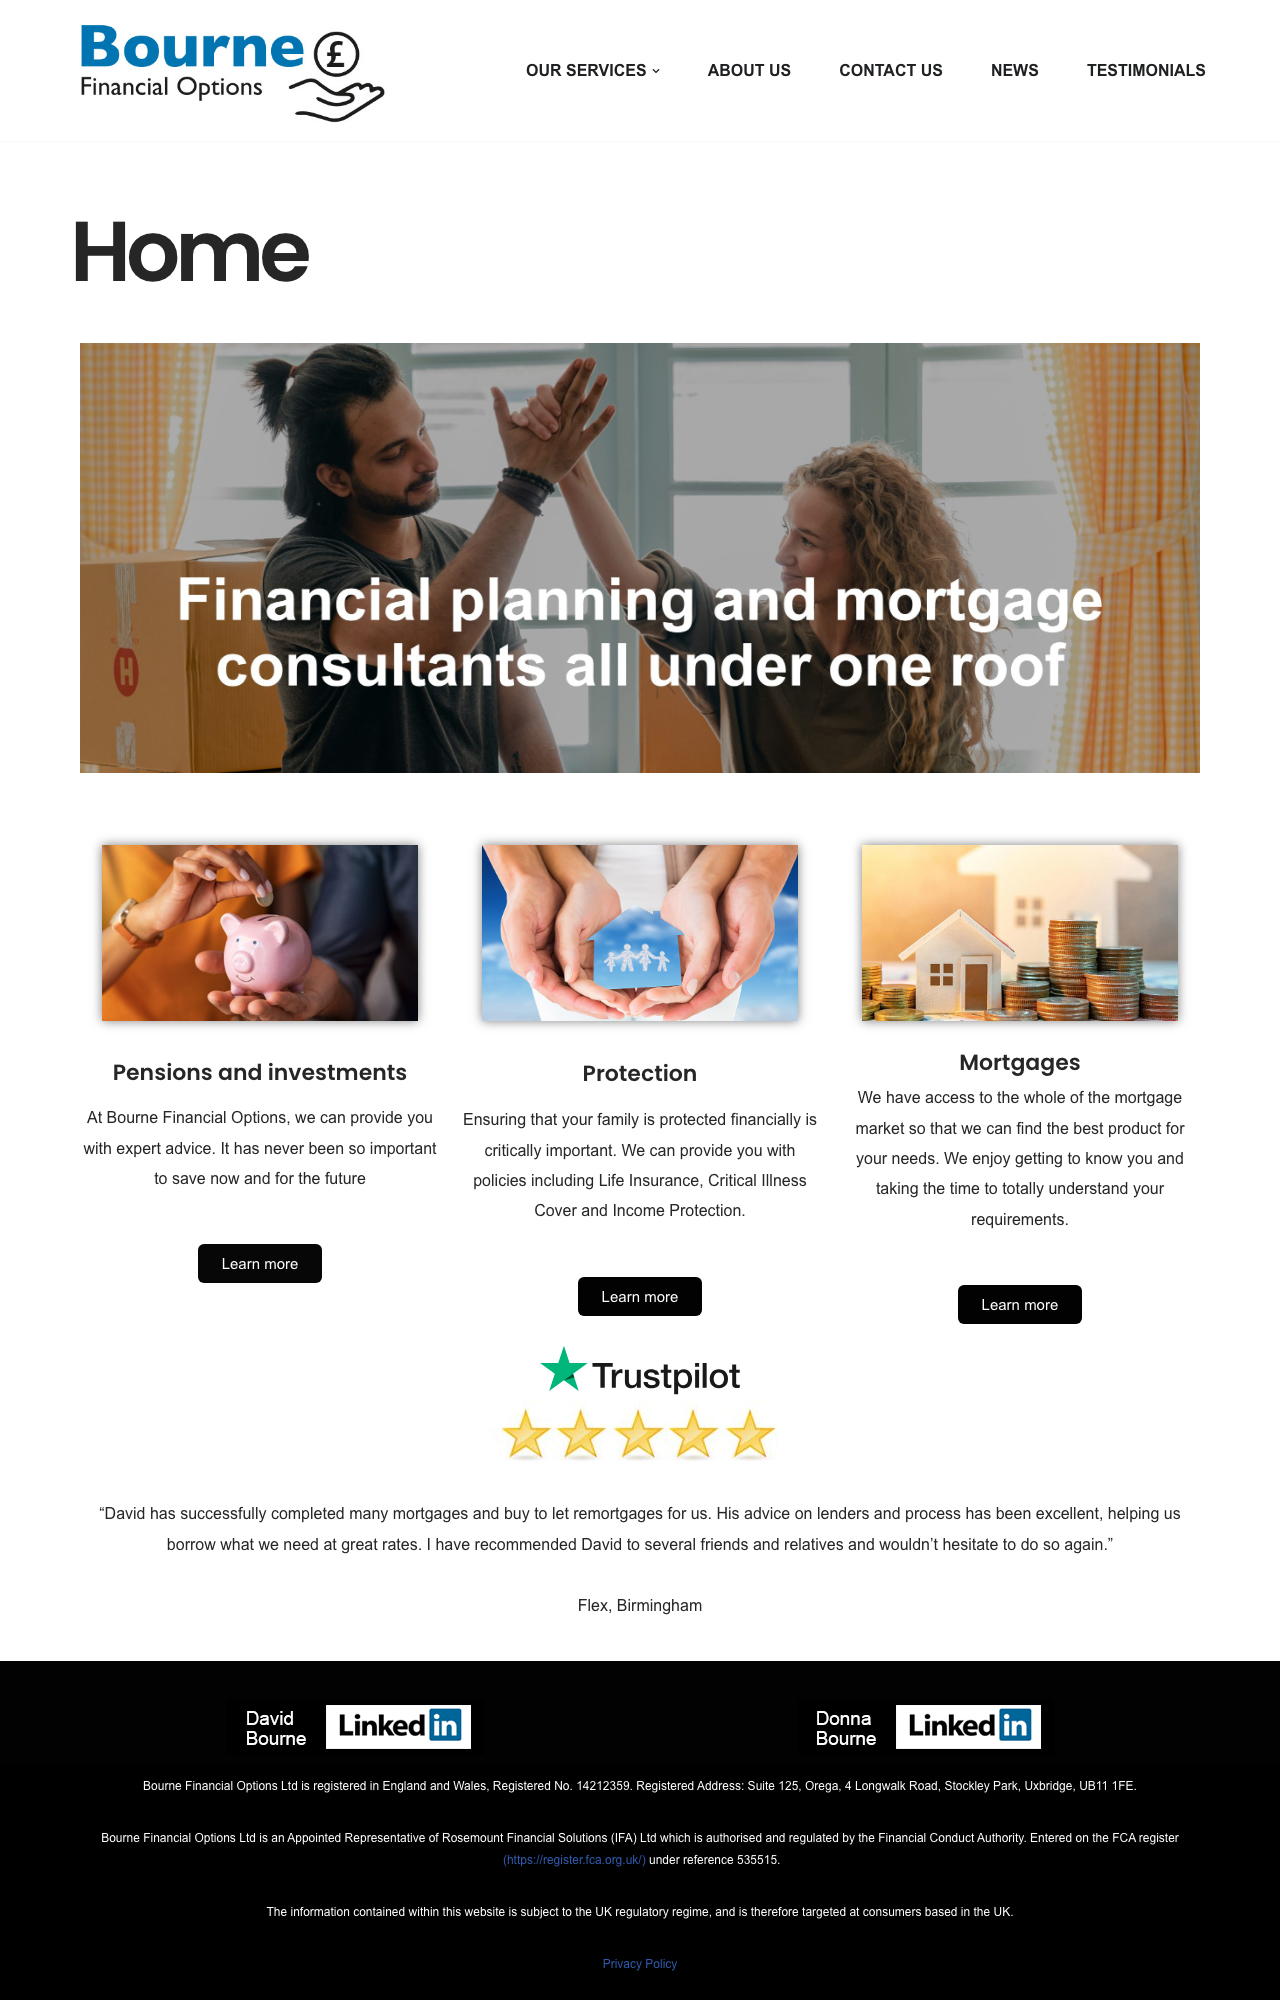
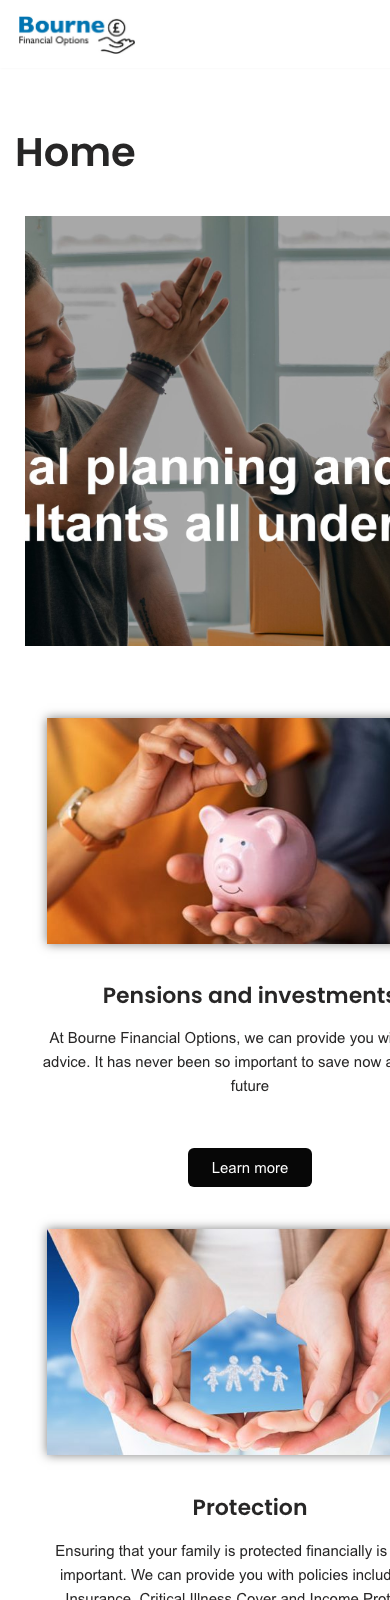
The same homepage on a laptop and a phone. About 270 words, no phone number, no enquiry form, and nothing that says what David is best at.
A · Front Door — established, warm, personal
A dark navy opener with a brass accent and a serif headline, then warm cream below. The version that reassures the clients he already has while the specialist pages do the finding. Fraunces for headlines, Public Sans for text.
Twenty years of getting mortgages over the line.
Twenty years of mortgages for people who own more than one.
I'm David. Since 2004 I've arranged mortgages for people all over the country — including plenty whose credit file has a bit of history on it.
I'm David. Since 2004 I've arranged mortgages for landlords — from a first buy-to-let to portfolios held in limited companies.
- Whole of market, including lenders you can't approach yourself
- No fee for the first conversation
- Authorised and regulated through Rosemount
[ placeholder photo — David's own to replace ]
A credit file with history on it isn't a closed door.
It's a reason to talk to someone who knows which lenders read the story rather than the score. Most of the people I help have already been told no somewhere else.
- CCJs and defaultsSatisfied or not, recent or historic. The age and the reason matter more than the number.
- Missed paymentsOn a mortgage, a car loan or a card — there are lenders who will still talk to you.
- Debt management plans and IVAsDuring one or after it. The route differs, and I'll tell you which one you're on.
- Turned down elsewhereOften it was the wrong lender in the wrong order, not a verdict on you.
Once you own a few, the high street starts saying no.
Rarely with an explanation. Landlord lending has its own rules, its own lenders and its own paperwork, and that's the part I enjoy.
- Limited company buy to letBuying through a company, or moving what you already own into one.
- HMOs and multi-unit blocksValued on rental income rather than bricks — a different set of lenders entirely.
- Four or more mortgaged propertiesThat makes you a portfolio landlord, with tougher stress testing. I handle the paperwork.
- Releasing equity to buy againAcross several properties at once, timed around your fixes ending.
Three steps, and I do most of them.
Tell me the situation, warts and all. Nothing you say will surprise me, and it costs nothing.
Who will lend, on what terms, and what it actually costs. You get a straight answer, even when it's no for now.
The application, the paperwork and the chasing, until the offer lands on your mat.
[ example cases — David's own, anonymised and approved ]
"David has a natural ability to make you feel comfortable and deals with you personally."
Tina, Windsor · a client for twenty years
- "Care and support from the moment you meet them."Paul, London
- "Simple explanations that gave us confidence."Katherine & Lee, first-time buyers
The questions I'm asked most
No. How old it is, whether it's satisfied and how large it was all matter more than its existence.
Usually more than the adverts suggest and less than people fear. It depends on what's on the file and when.
Not if we do it in the right order. Knowing that order is a good part of what you're paying me for.
It's a tax question first. I'll work alongside your accountant rather than guess at it.
Four or more mortgaged properties makes you a portfolio landlord, and lenders must assess the whole portfolio.
Often yes, and sometimes across several properties at once. It's the job I like most.
Tell me the situation and I'll tell you where you stand.
Book a chatB · Plain English — direct, modern, built to convert
Heavy sans headlines, deep green, and a checker on the homepage. The version that competes hardest for strangers arriving from Google: it answers the question before it sells. Archivo throughout.
Been told no? That's usually not the end of it.
Own a few properties? The next one gets easier.
CCJs, defaults, missed payments, a debt plan. I'm David Bourne, and finding lenders for exactly this is what I've done for twenty years.
Limited company buy to let, HMOs, portfolios of four or more. I'm David Bourne, and I've arranged landlord mortgages for twenty years.
- Two minutes, no credit check, no obligation
- A real person, not a comparison site
The questions everybody asks me.
The questions landlords ask me.
No. How old it is, whether it's satisfied and how big it was all matter more.
More than the adverts suggest, less than people fear. It depends on the file.
Not when we do it in the right order. That's half of what you're paying me for.
A tax question first. I'll work with your accountant rather than guess.
Four or more mortgaged properties triggers portfolio rules and tougher stress testing.
Often, and across several properties at once.
[ placeholder photo — David's own to replace ]
"David was great in finding me the perfect mortgage to meet my needs."
Clare · Trustpilot
- 12 five-star reviewsand more on the way
- Twenty years, one adviseryou deal with David, every time
Tell me the situation. I'll tell you what's possible.
Book a chatC · Case Notes — expert, editorial, quietly premium
Cream paper, charcoal type, burgundy accent, and real case snippets in the margin. This one says "specialist" loudest and suits landlord and complex work best. Spectral for headlines, Public Sans for text.
The cases other brokers hand back.
Mortgages for people who own more than one.
Credit files with history on them. Twenty years of knowing which lender reads the story rather than the score.
Limited companies, HMOs and portfolios. Twenty years of knowing which lender prices them properly.
[ placeholder photo — David's own to replace ]
Case notes.
[ example cases — David's own, anonymised and approved ]
Specialist work, explained without the jargon.
- Adverse creditCCJs, defaults, missed payments, debt management plans, discharged bankruptcy.
- After a declineA refusal isn't a verdict. Often it's the wrong lender, in the wrong order.
- First-time buyersIncluding the ones told to come back in three years.
- Limited company buy to letSPVs, directors' loans, and the lenders who understand both.
- HMOs and multi-unit blocksLicensing, Article 4, and valuations on rental income.
- Portfolio remortgagesFour or more mortgaged properties, handled as one piece of work.
"David and Donna give you a feel of care and support from the moment you meet them."
Paul, London · client for seven years
Twelve five-star reviews, and clients who have stayed twenty years. That is the whole argument, really.